Owner with group benefits
You have coverage through the business, but personal responsibilities may call for a separate review.
As your role, income or responsibilities change, your insurance may need another look. PLA reviews existing coverage, identifies potential gaps and helps you evaluate relevant individual insurance options in the context of your business.
You may have insurance through work, personally or through your business. Understanding whether those arrangements still fit together can be difficult as your responsibilities change.
The value of a review depends on the person’s situation, not an assumption that more insurance is needed.
You have coverage through the business, but personal responsibilities may call for a separate review.
Your compensation and financial obligations may differ from what the standard group arrangement was designed to address.
Distinguish protection for yourself from insurance intended to fund obligations between owners.
The business may face continuity concerns involving someone who is not a shareholder. Those risks should be considered separately from the person’s individual coverage needs.
Coverage can remain in place while the circumstances around it change. Without a review, it may be difficult to know whether the protection still addresses the needs it was intended to meet.
Additional coverage is not automatically the right answer. Existing arrangements, individual circumstances and business needs determine what warrants review.
The appropriate type of individual insurance depends on the need identified, current coverage, personal and business circumstances, product availability and applicable underwriting.
The process starts with existing protection and the person’s responsibilities, not a presumption that another policy is required.
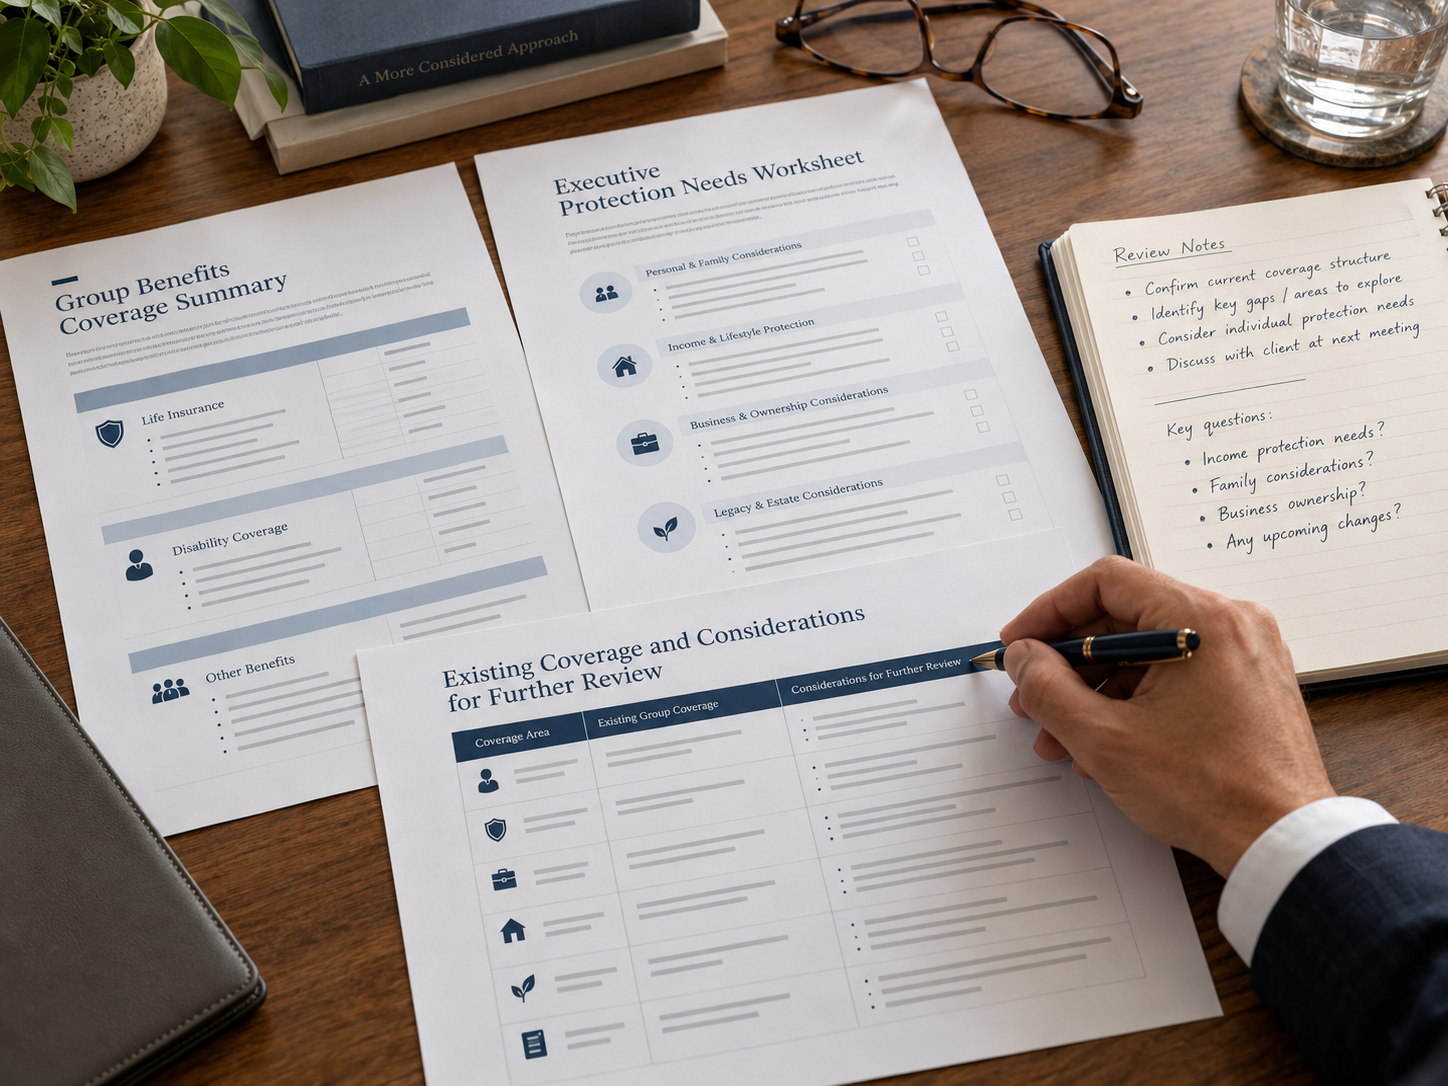
Review current group coverage, limits and relevant definitions.
Clarify role, income, ownership position, obligations and business considerations.
Examine where existing coverage may fall short of the stated need.
Review insurance structures and insurers when the facts, current availability and underwriting requirements support comparison.
Connect the decision to buy-sell or continuity planning where those needs overlap.
Proceed through the applicable provider-specific process only after the need and scope are understood.
Addresses protection needs for an owner, executive or other individual that may sit beyond the group plan.
Addresses shareholder obligations, ownership funding and business continuity risk.
The same person or business circumstance can create both questions. Review them together when useful, without assuming one type of insurance addresses the other.
PLA also assists with Visitors-to-Canada insurance. Coverage and eligibility depend on the visitor’s circumstances and available products. Start with a conversation so PLA can review the relevant details and explain the next step.
Start a ConversationCoverage, exclusions, eligibility, underwriting and pricing are provider- and product-specific. No instant pricing is available through this website.
A useful review should explain why an option is being considered, not simply present another policy.
The review begins with the protection already in place rather than assuming a new policy is necessary.
Relevant options are considered against the identified need, not presented as a product list.
Individual protection, ownership obligations and business continuity can be reviewed together without treating them as interchangeable.
Final availability and terms depend on the applicable insurer, product and underwriting process.
Group plan limits, definitions and structure may not fully reflect an owner’s or executive’s income, responsibilities or financial obligations. Review the actual group provisions alongside the person’s circumstances before concluding that a gap exists.
A review can be useful when responsibilities, compensation, ownership or personal circumstances change, or when policies arranged earlier may no longer reflect current needs.
No. The need depends on existing coverage, individual circumstances and the purpose of the protection. A review helps determine whether any change warrants consideration.
Individual coverage addresses personal protection needs beyond the group plan. Buy-sell and key-person arrangements address ownership obligations and business continuity. The decisions may overlap, but they serve distinct purposes.
No. PLA first needs to understand the circumstances and complete appropriate fact finding. Availability, terms and suitability depend on the insurer, product and underwriting process.
Visitors-to-Canada insurance is an active PLA specialty. PLA reviews the visitor’s circumstances and relevant eligibility information before providing formal information through the applicable process. Instant website pricing is not available.
The goal is to understand the protection already in place, what may need attention and whether a change is appropriate for the person and the business.
Start with a conversation about the coverage you have, what has changed and what you want to understand. PLA will follow up by email with appointment options for a discovery and fact-finding conversation.
Existing client? Contact PLA directly or use your regular review process.
Explore Buy-Sell & Key-Person Insurance